Retirement planning is often something couples do together.
You discuss when you’ll stop working, where you want to live, how much money you’ll need, and what you hope to enjoy during your retirement years.
You may also coordinate Social Security benefits, pensions, investment accounts, and other financial resources to create a retirement income strategy that supports both of you.
But there’s one important question I encourage married couples to consider:
What happens to your retirement income if one spouse passes away?
It’s not an easy conversation, and I understand why many people would rather avoid it.
However, planning for the financial well-being of a surviving spouse is one of the most meaningful parts of creating a thoughtful retirement strategy.
When one spouse dies, household income may decrease, Social Security benefits can change, pension payments may be reduced, and taxes may become more complicated.
Meanwhile, many household expenses continue.
As a financial advisor in San Diego with more than 28 years of experience, I believe retirement planning should consider not only the years you hope to spend together but also the financial security of the spouse who may live longer.
Let’s explore what can happen to retirement income after the loss of a spouse and how couples can prepare.
Quick Answer: What Happens to Retirement Income When a Spouse Dies?
When one spouse passes away, the surviving spouse’s retirement income may change in several important ways:
- Social Security: The surviving spouse may qualify for survivor benefits based on the deceased spouse’s work record, but generally cannot collect two full Social Security retirement benefits.
- Pensions: Payments may continue, decrease, or stop depending on the pension’s survivor benefit provisions.
- 401(k)s and IRAs: The surviving spouse may inherit retirement accounts, subject to beneficiary designations and applicable distribution rules.
- Taxes: A change in filing status may affect federal and California income taxes.
- Medicare premiums: Changes in income and filing status may affect income-related Medicare premiums.
- Household expenses: Housing, property taxes, insurance, and other costs may remain even when household income declines.
The financial impact depends on your specific benefits, investments, insurance coverage, retirement accounts, and other resources.
For many couples, preparing for these changes before retirement can be an important part of protecting the surviving spouse’s financial future.
Why Survivor Income Planning Is So Important
When couples plan for retirement, they often start by adding their expected income sources together.
For example, one spouse might receive Social Security benefits while the other receives Social Security and a pension.
They may also have retirement savings that can supplement their household income.
Together, these resources may provide enough income to support the retirement lifestyle they’ve envisioned.
But what happens when one of those income sources ends?
The surviving spouse may still need to pay for housing, transportation, healthcare, utilities, groceries, insurance, and other living expenses.
Some costs may decrease, but others may remain relatively unchanged.
That creates an important financial planning challenge.
A Hypothetical Example: How Household Retirement Income Can Change
Imagine a retired couple receiving the following monthly Social Security benefits:
| Income source | Monthly amount |
| Spouse A’s Social Security | $3,100 |
| Spouse B’s Social Security | $1,800 |
| Combined Social Security income | $4,900 |
Now imagine Spouse A passes away.
If Spouse B qualifies for a survivor benefit equal to Spouse A’s full $3,100 benefit, the household’s ongoing Social Security income might change as follows:
| Before and after | Monthly Social Security income |
| Both spouses living | $4,900 |
| Surviving spouse | $3,100 |
| Monthly reduction | $1,800 |
That’s a reduction of approximately 37% in monthly Social Security income.
This is a simplified illustration. Actual survivor benefits depend on factors such as eligibility, claiming age, and the deceased worker’s benefit history.
But it demonstrates why retirement planning should consider what happens when a household changes from two people receiving benefits to one.
A surviving spouse may experience a significant income reduction even though many expenses remain.
1. What Happens to Social Security When Your Spouse Dies?
Social Security is often one of the most important sources of retirement income for married couples.
However, many retirees misunderstand how benefits change after a spouse passes away.
Can a Surviving Spouse Receive Both Social Security Benefits?
Generally, no.
A surviving spouse who qualifies for both their own retirement benefit and a survivor benefit based on their deceased spouse’s record generally receives the higher applicable benefit amount, not both full amounts added together.
For example, if your own retirement benefit is $1,800 per month and you qualify for a $3,100 survivor benefit, your total monthly benefit may increase to $3,100.
It generally would not become $4,900.
This distinction is especially important for couples who rely on both Social Security payments to support their retirement lifestyle.
At What Age Can You Receive Social Security Survivor Benefits?
Eligibility depends on individual circumstances.
Generally, a surviving spouse may qualify for survivor benefits beginning at age 60, or age 50 if they meet applicable disability requirements.
Certain individuals caring for an eligible child may qualify at a younger age.
Starting survivor benefits before survivor full retirement age generally reduces the monthly amount.
At survivor full retirement age, an eligible person may receive up to 100% of the deceased spouse’s applicable benefit, subject to Social Security rules.
Why Claiming Decisions Matter for Married Couples
The age at which each spouse claims Social Security may affect household income during retirement and the benefits available after one spouse dies.
For some couples, delaying the higher earner’s retirement benefit may increase the survivor benefit potentially available to the other spouse.
However, the appropriate strategy depends on health, financial circumstances, income needs, and other considerations.
Eligible survivors may also have options to claim survivor benefits and their own retirement benefits at different times.
I encourage couples to evaluate these decisions together rather than assuming that the earliest available claiming date is always the best choice.
You can learn more through the Social Security Administration’s survivor benefits information.

2. What Happens to Pension Income After a Spouse Dies?
If one or both spouses receive a pension, the financial impact of a death may depend heavily on the payment option selected.
This is one of the most important details to review before retirement begins.
Some pensions offer different payment arrangements, including options that provide income only during the retiree’s lifetime and options designed to continue some payments to a surviving spouse.
Single-Life Pension Benefits
A single-life pension generally provides payments for the retiree’s lifetime.
Depending on the pension arrangement, payments may stop when that retiree dies.
For married couples, choosing this type of benefit can create additional financial risk for the surviving spouse if no other survivor protection is available.
Joint-and-Survivor Pension Benefits
A joint-and-survivor pension is generally designed to continue a specified portion of pension income after the original retiree dies.
Depending on the plan and election, the surviving spouse might receive a percentage such as 50%, 75%, or 100% of the applicable benefit.
These percentages are examples, not guarantees of what any particular pension plan offers.
A Hypothetical Pension Example
Imagine a retiree receives a monthly pension of $4,000.
If the selected pension option provides a 50% survivor benefit, the surviving spouse could receive $2,000 per month after the retiree’s death.
Under a qualifying 100% survivor option, the surviving spouse could continue receiving the applicable full benefit.
However, pension options that provide survivor protection may also offer a lower initial monthly payment than a single-life option.
The available choices depend on the specific pension plan.
Questions to Ask About Your Pension
Before retirement, consider asking your employer or pension administrator:
- Does my pension include survivor benefits?
- What percentage would my spouse receive?
- Does the benefit change after my death?
- What elections must be made before retirement?
- Can survivor benefit elections be changed later?
- Are there additional benefits or restrictions we should understand?
Certain pension elections may be difficult or impossible to change after benefits begin.
That’s why this conversation is best held before the retirement paperwork is finalized.
The IRS explains retirement-plan survivor protections and the importance of reviewing your plan’s terms.
3. What Happens to a 401(k) or IRA When a Spouse Passes Away?
Retirement accounts are another important piece of the survivor income discussion.
If your spouse passes away, you may inherit assets held in an IRA, 401(k), or another retirement plan.
However, the options available depend on several factors, including:
- The account type
- The beneficiary designation
- Your relationship to the original owner
- Whether the original owner had begun required minimum distributions
- Applicable plan rules
- Current tax law
Inheriting an IRA From Your Spouse
A surviving spouse who inherits an IRA may have certain options that are not available to other beneficiaries.
Depending on the circumstances, these may include treating the inherited IRA as their own or maintaining an inherited IRA arrangement.
The choice can affect withdrawal timing, required minimum distributions, and potential additional taxes on early withdrawals.
It is not always beneficial to immediately move an inherited IRA into your own account.
For example, a younger surviving spouse who may need access to inherited retirement assets before age 59½ should understand how the different arrangements affect withdrawal rules.
Inheriting a 401(k)
If the deceased spouse participated in an employer-sponsored retirement plan, the surviving spouse should contact the plan administrator to determine the available benefits.
Depending on the account and applicable rules, options may include maintaining certain inherited benefits, rolling over eligible funds, or taking permitted distributions.
The appropriate choice depends on the retirement plan and the surviving spouse’s financial circumstances.
Why Beneficiary Designations Matter
Retirement accounts generally have beneficiary designations that help determine who receives the assets after the account owner’s death.
Those designations should be reviewed periodically, especially after marriage, divorce, the birth of a child, or another significant life event.
Couples should also consider how beneficiary decisions fit into their estate planning documents.
A qualified estate planning attorney can help address the legal considerations involved.
My recommendation is to review retirement account beneficiaries before a major life event forces your family to address these decisions under pressure.
For details about inherited retirement account rules, visit the IRS retirement beneficiary guidance.
4. How Taxes May Change After the Death of a Spouse
Taxes are another area where surviving spouses may encounter unexpected changes.
While losing a spouse can reduce household income, the surviving spouse’s tax situation may also change.
Married Filing Jointly vs. Single Filing Status
For federal income tax purposes, a surviving spouse may generally be eligible to file a joint return for the year their spouse dies, provided they meet the applicable requirements.
After that year, the surviving spouse’s filing status may change.
Some individuals with qualifying dependent children may be eligible for the qualifying surviving spouse filing status for a limited period.
However, many older retirees without qualifying dependents may eventually file as single taxpayers if they do not remarry and do not qualify for another filing status.
Why This Matters for Retirement Income
Different filing statuses can have different standard deductions, tax brackets, and income thresholds.
For example, a surviving spouse might continue receiving pension payments, retirement account withdrawals, and investment income while moving from a married filing jointly tax situation to single filing status.
That combination can affect how much money remains available after taxes.
California Retirement Tax Considerations
California income taxes should also be part of the discussion.
Depending on the financial accounts and income involved, the surviving spouse may need to review:
- Retirement account distributions
- Pension income
- Investment income
- Real estate income
- Capital gains
- Changes in filing status
California does not tax Social Security benefits, but other retirement income may be taxable.
The tax treatment of inherited assets can also be complex.
I believe these decisions should be coordinated with a qualified tax professional and, where appropriate, an estate planning attorney.
A thoughtful retirement income strategy considers the amount available after applicable taxes, not just the amount appearing on a financial statement.
5. Could Medicare Premiums Change After a Spouse Dies?
Yes, Medicare premiums may also become part of the financial adjustment.
Some Medicare beneficiaries pay an income-related adjustment to their Part B and Part D premiums.
This additional amount is commonly called IRMAA, or the Income-Related Monthly Adjustment Amount.
The calculation generally considers modified adjusted gross income and filing status, often using tax return information from two years earlier.
Why a Surviving Spouse May Face Different Medicare Costs
After a spouse dies, household income and tax filing status may change.
For some surviving spouses, that could affect future Medicare premium calculations.
However, Social Security recognizes the death of a spouse as a qualifying life-changing event for certain IRMAA reconsideration requests.
If the death of a spouse results in reduced household income, an eligible individual may be able to request a new determination.
Social Security provides information about this process and Form SSA-44.
The rules depend on the circumstances, and not every request results in a reduced premium.
Still, it’s an important option to know about.
6. Why Household Expenses Don’t Always Decrease as Much as Income
One of the most common assumptions about retirement expenses is that a household with one person will cost significantly less than a household with two people.
While some expenses may decrease, many essential costs remain.
Consider the following:
Housing: A mortgage payment or rent may remain the same.
Property taxes: Property-related expenses may continue, subject to any applicable legal changes.
Insurance: Homeowners insurance and certain other policies may remain necessary.
Utilities: Electricity, water, internet, and other household services still need to be paid.
Transportation: The surviving spouse may still need a vehicle, maintenance, and insurance.
Healthcare: Medical and prescription expenses may continue or change with age.
Home maintenance: Repairs, landscaping, and upkeep may remain necessary.
Daily living expenses: Groceries and other spending may decrease, but they rarely disappear.
This is why I encourage couples to consider two retirement budgets.
The first reflects the lifestyle and expenses they expect while both spouses are living.
The second considers the financial circumstances of the surviving spouse.
The difference between those two budgets may reveal an important retirement income gap.
7. How Life Insurance May Help Protect a Surviving Spouse
Life insurance can be another resource to consider as part of a comprehensive retirement plan.
Depending on the policy and beneficiary arrangements, a death benefit may provide funds that can help a surviving spouse address immediate expenses, pay down debt, or supplement available financial resources.
However, not every policy provides the same benefits.
Coverage amounts, premiums, exclusions, policy values, and payout provisions can vary.
Some individuals may have life insurance through their employer that changes or ends when they retire.
Others may have personally owned policies or permanent life insurance coverage.
Before retirement, review whether existing policies still meet your family’s needs.
It’s also important to consider how insurance proceeds interact with investments, taxes, estate planning, and other financial priorities.
A policy should be evaluated based on your specific needs and circumstances rather than assuming more insurance is always the answer.

8. How Couples Can Prepare for Survivor Retirement Income Needs
The good news is that couples don’t have to wait until a difficult life event occurs to begin planning.
There are several useful steps that can help clarify what retirement income might look like after the loss of a spouse.
Step 1: List Your Retirement Income Sources
Identify expected income from:
- Social Security
- Pensions
- Traditional and Roth retirement accounts
- Taxable investments
- Annuities
- Rental properties
- Business interests
- Other available sources
Then determine which income streams are expected to continue if one spouse dies.
Step 2: Review Social Security Survivor Benefit Estimates
Look at each spouse’s projected Social Security benefits and evaluate how survivor benefits might work under different claiming scenarios.
Use personalized information from the Social Security Administration instead of relying on generalized assumptions.
Step 3: Review Pension Elections
If either spouse has a pension, understand the available survivor benefit options before selecting a payment arrangement.
This is particularly important when those decisions may become permanent once pension payments begin.
Step 4: Evaluate Retirement Account Beneficiaries
Review beneficiary designations and confirm they are consistent with your current goals and estate planning documents.
Understand how inherited accounts may be distributed and what deadlines or tax considerations could apply.
Step 5: Create a Survivor Retirement Budget
Estimate how much monthly income the surviving spouse may need.
Consider housing, healthcare, insurance, taxes, transportation, personal expenses, and other obligations.
Then compare those expenses with the income sources expected to remain.
Step 6: Review Insurance and Other Financial Resources
Determine whether existing insurance policies, cash reserves, investments, or other resources could help address potential income gaps.
The objective is not to purchase unnecessary products. It is to understand the resources you already have and evaluate whether they align with your needs.
Step 7: Coordinate Your Financial and Estate Planning
Your financial advisor, CPA, estate planning attorney, and insurance professionals may each have an important role in preparing a coordinated plan.
Retirement income, beneficiary designations, tax decisions, and estate documents should work together.
What Should You Do Financially After Your Spouse Passes Away?
Even with a well-prepared retirement plan, losing a spouse can be overwhelming.
There may be important financial decisions to make, but not every decision needs to happen immediately.
When possible, avoid rushing into major investment changes or financial commitments before understanding your options.
A practical starting checklist includes:
- Obtain necessary death certificates and important records.
- Contact Social Security about survivor benefits and any applicable lump-sum death payment.
- Contact pension and retirement plan administrators.
- Notify life insurance companies and review applicable benefits.
- Identify immediate bills, income sources, and available cash.
- Review beneficiary designations and account ownership with qualified professionals.
- Speak with a CPA about changes to tax filing status and retirement distributions.
- Review any Medicare income-related premium adjustments.
- Update your household income plan and budget.
- Consult an estate planning attorney regarding legal and estate matters.
The appropriate sequence may differ depending on the family’s circumstances.
I encourage surviving spouses to seek guidance before making major financial decisions, particularly when retirement accounts, real estate, inheritances, or tax consequences are involved.
Retirement Planning for Married Couples in San Diego
San Diego couples may face additional considerations because of housing costs, real estate assets, healthcare expenses, and the financial resources they’ve accumulated throughout their careers.
Some households rely primarily on Social Security and retirement investments.
Others have pensions, business interests, rental properties, or multiple retirement accounts.
Each situation is different.
A plan that works comfortably for two people may need adjustments when only one person remains.
That’s why I believe a comprehensive retirement strategy should consider both spouses’ financial needs and potential changes over time.
Through COPIA Wealth Management & Insurance Services, our team helps individuals and families explore personalized retirement income planning, investment considerations, wealth preservation, and financial strategies aligned with their goals.
The goal is not to predict the future.
It’s to prepare thoughtfully for the financial circumstances that could affect the people you love.
Recommended Reading: Retirement By Design
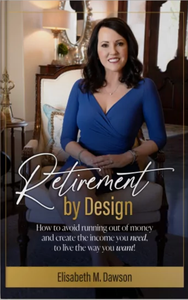
One of the most meaningful parts of retirement planning is preparing for the future while also considering the financial well-being of your loved ones.
In my book, Retirement By Design: How to Avoid Running Out of Money and Create the Income You Need, To Live the Way You Want!, I explore important retirement risks, income-planning decisions, and steps families can consider when creating a more thoughtful financial future.
My goal is to help you approach retirement with greater clarity about the financial decisions that matter most.
Explore Retirement By Design and Get Your Copy →
My Perspective: Retirement Planning Should Protect the Life You’ve Built Together
Throughout my career, I’ve believed financial planning should help people create a life by design, not by default.
For married couples, that means looking beyond today’s financial circumstances and considering what the future may bring.
When you’re planning retirement with someone you love, your goals are often shared.
But the financial plan must also consider what happens if one spouse is left to navigate retirement alone.
That may involve Social Security, pensions, retirement accounts, taxes, housing, insurance, and other important considerations.
I believe these conversations are worth having early, even when they’re uncomfortable.
A thoughtful retirement income strategy should help both spouses understand how their financial resources may support them throughout retirement—even when life doesn’t unfold exactly as planned.
Let’s Talk About Your Retirement Income Strategy
Are you and your spouse preparing for retirement?
Have you wondered whether your current income plan would still work if one of you passed away?
Or are you a surviving spouse trying to understand how your finances may change?
Our team at COPIA Wealth Management & Insurance Services welcomes the opportunity to help you explore your financial planning options.
We can review your retirement income goals, financial resources, investment considerations, and important questions about the future.
You can also explore our Retirement Income for Life Blueprint, designed to help you begin evaluating the income sources and retirement goals that matter most.
Explore Your Retirement Income for Life Blueprint
Schedule a Conversation With Our Team
Call: (619) 640-2622
Serving: San Diego County and surrounding communities.
Frequently Asked Questions About Retirement Income After a Spouse Dies
Does a surviving spouse receive both Social Security checks?
Generally, no. A surviving spouse eligible for both their own retirement benefit and a survivor benefit typically receives the higher applicable amount rather than both full benefits combined. Actual benefits depend on claiming age and other Social Security rules.
Will my pension continue after my spouse dies?
It depends on the pension plan and the payment option selected. Some arrangements provide ongoing survivor benefits, while others may reduce or stop payments after the original retiree dies. Review the plan documents and contact the pension administrator to confirm the specific benefits.
What happens to my spouse’s 401(k) when they die?
The account is generally handled according to beneficiary designations and applicable plan rules. A surviving spouse may have different options for inherited funds, including certain rollover or distribution choices, depending on the circumstances. Contact the plan administrator before making decisions.
Can a surviving spouse inherit an IRA without paying taxes immediately?
Certain spousal inheritance or rollover arrangements may allow eligible retirement assets to remain tax-deferred. However, the rules depend on the account, beneficiary status, distribution method, and timing. A lump-sum taxable distribution may produce a different result. Review the options with a qualified tax professional.
Will my taxes increase after my spouse passes away?
They may, but not necessarily. A surviving spouse’s tax filing status, taxable income, deductions, and financial circumstances can change. Some individuals may pay a higher effective tax rate on certain income after moving from married filing jointly to single filing status.
Can Medicare premiums change after the death of a spouse?
Yes. Changes in income and tax filing status may affect income-related Medicare premiums. If the death of a spouse reduces household income, certain beneficiaries may be eligible to request a new IRMAA determination through Social Security.
Should married couples plan for survivor income before retirement?
Yes. Reviewing Social Security, pensions, retirement accounts, insurance, and household expenses before retirement can help couples identify possible financial gaps and make more informed decisions.
What is the most important first step in survivor retirement planning?
Begin by identifying which household income sources would continue after the death of either spouse. Then compare the remaining income with estimated living expenses. This helps reveal whether additional planning may be necessary.