
Planning for retirement involves more than deciding when to stop working or how much money to save. It also means preparing for expenses that could change your financial future, including the possibility of needing long-term care.
One of the questions I encourage individuals and families to consider is simple: How would you pay for long-term care if you or someone you love needed it?
It’s a question many people avoid because they don’t know where to begin. Others assume Medicare will cover the expense, their savings will be enough, or family members will be available to help.
Unfortunately, those assumptions can create financial challenges later.
As a financial advisor in San Diego with more than 28 years of experience, I’ve learned that thoughtful retirement planning means considering both the life you hope to enjoy and the unexpected expenses you may face.
Let’s explore the different ways to pay for long-term care in San Diego and how these options may fit into a larger retirement strategy.
Quick Answer: How Do You Pay for Long-Term Care?
There are several ways to pay for long-term care, including:
- Personal savings and portfolio assets: Using retirement income, savings, or other assets to cover care expenses.
- Traditional long-term care insurance: Purchasing a policy designed to cover qualifying long-term care services.
- Hybrid life insurance and long-term care policies: Combining certain life insurance benefits with long-term care coverage.
- Medi-Cal: California’s Medicaid program, which may help eligible individuals pay for qualifying long-term care services.
- Veterans benefits: Certain VA programs may help eligible veterans access or pay for care.
- Other financial resources: Pensions, Social Security, eligible home equity arrangements, and other sources of income or assets.
The right approach depends on your age, health, financial resources, existing insurance, family responsibilities, and retirement goals.
For many San Diego families, combining multiple funding sources may provide greater flexibility than relying entirely on one option.
Why Paying for Long-Term Care Deserves a Place in Your Retirement Plan
When most people imagine retirement, they picture travel, family time, hobbies, and enjoying the wealth they’ve worked hard to build.
But retirement can also bring changing healthcare and personal care needs.
Long-term care generally refers to ongoing assistance for people who need help with everyday activities, including:
- Bathing and dressing
- Eating and personal hygiene
- Moving around safely
- Managing certain daily routines
- Receiving supervision because of cognitive impairment
- Living safely at home or in a care community
These services may be provided through in-home caregivers, adult day programs, assisted living communities, or nursing facilities.
The financial challenge is that long-term care expenses can continue for months or years, depending on individual circumstances.
In San Diego, the cost also depends on the type and amount of assistance needed.
For a closer look at local expenses, read my guide: How Much Does Long-Term Care Cost in San Diego?
Understanding potential costs is the first step. The next is deciding how those expenses might be paid without unnecessarily disrupting your retirement income or other financial goals.
Option 1: Paying for Long-Term Care With Personal Savings and Portfolio Assets
One common way to pay for long-term care is through personal savings and portfolio assets. This is often referred to as self-funding or self-insuring.
Instead of purchasing a separate insurance policy, you plan to use financial resources you already own.
These may include:
- Savings accounts and cash reserves
- Taxable investment accounts
- Retirement account withdrawals
- Pension income
- Social Security benefits
- Other portfolio holdings or available assets
For some individuals with substantial financial resources, self-funding may be a reasonable option.
However, the decision deserves careful consideration.
The Risk of Relying Entirely on Savings
Imagine entering retirement with a financial plan designed to support your preferred lifestyle for the next 25 or 30 years.
Your assets are intended to provide income for housing, travel, healthcare, family activities, and everyday living expenses.
Now imagine needing to withdraw additional money every month to pay for a caregiver or care facility.
Those withdrawals could affect other parts of your retirement strategy.
Potential challenges include:
Reduced retirement assets. Money spent on care is no longer available to support other retirement expenses.
Additional taxes. Withdrawals from certain retirement accounts may create taxable income.
Market timing risk. Selling assets during a market decline to cover care expenses could affect your long-term portfolio.
Impact on your spouse. If one spouse requires expensive care, the remaining spouse may still need retirement income for many years.
Changes to your legacy plans. Significant care expenses could reduce the assets available for your family or other beneficiaries.
Self-funding doesn’t necessarily mean making a poor financial decision. It means understanding how a potentially large care expense fits into the rest of your plan.
When Self-Funding May Make Sense
Using personal assets may be more appropriate when you have substantial financial resources, sufficient liquidity, and a retirement strategy that can accommodate unexpected expenses.
The key is evaluating potential care costs before the need arises—not simply assuming your portfolio will cover them.
Option 2: Traditional Long-Term Care Insurance
Traditional long-term care insurance is designed to help pay for qualifying care expenses when an insured person meets the policy’s benefit requirements.
Depending on the policy, coverage may include:
- Care received at home
- Assisted living services
- Nursing facility care
- Adult day care
- Other eligible personal care services
Policies vary significantly, so understanding the details is essential.
How Long-Term Care Insurance Typically Works
You purchase a policy and pay premiums to maintain coverage.
If you later qualify for benefits under the policy, the insurance company may pay or reimburse covered expenses, subject to the policy’s terms and limits.
Common policy features include:
Daily or monthly benefit amount: The maximum amount available for qualifying care expenses.
Benefit period or pool of money: How much coverage may be available over the life of the policy.
Elimination period: A waiting period or other requirement before benefits begin.
Inflation protection: A feature intended to help coverage keep pace with rising care costs.
Benefit triggers: Requirements involving assistance with activities of daily living or cognitive impairment.
Not every policy works the same way. Some reimburse eligible expenses, while others may provide cash benefits.
The California Department of Insurance provides consumer guidance explaining coverage, policy structures, and important questions to ask.
Advantages of Traditional Long-Term Care Insurance
A policy may help reduce the amount of personal savings needed to pay for covered care.
It can also create a dedicated source of funding for qualifying expenses, helping families plan more deliberately.
Potential Disadvantages
Traditional policies may involve significant premiums, underwriting requirements, benefit limitations, and potential future premium increases.
Some people may not qualify for coverage because of health conditions.
Others may decide that the cost or structure of available policies doesn’t fit their needs.
My perspective: Long-term care insurance should be evaluated as part of your complete financial strategy, not simply as an isolated insurance purchase.
Option 3: Hybrid Life Insurance and Long-Term Care Policies
Another option worth exploring is a hybrid policy that combines life insurance with certain long-term care benefits.
These products are sometimes called combination policies or linked-benefit policies.
Unlike traditional long-term care insurance, some hybrid products include a life insurance death benefit that may be available to beneficiaries if long-term care benefits are not fully used.
However, the exact structure depends on the policy.
How Hybrid Long-Term Care Policies Work
Certain hybrid policies allow qualifying long-term care expenses to be paid through an acceleration of the death benefit or through additional long-term care coverage.
In many cases, using long-term care benefits reduces the amount ultimately available to beneficiaries.
Some policies also include features such as additional care benefits beyond the death benefit, cash value provisions, or different premium-payment arrangements.
These features are not universal.
Why Some Families Consider Hybrid Policies
One concern I often hear about traditional insurance is the possibility of paying premiums for years and never needing care.
Hybrid products may appeal to individuals who want to explore both life insurance protection and long-term care coverage.
But they also involve tradeoffs.
Premiums can be substantial. Policy designs differ. Withdrawals, loans, benefit acceleration, and surrender provisions may affect the death benefit or other policy values.
It’s important to understand what happens if you need care, never need care, stop paying premiums, or change your financial plan.
Traditional and hybrid policies should be compared based on actual benefits, costs, and suitability—not simply the appeal of combining two financial products.
Recommended Reading: Retirement By Design
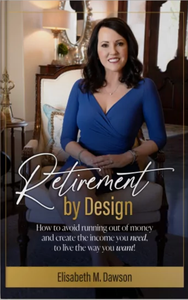
Preparing for retirement means planning for more than everyday living expenses. Unexpected healthcare costs, long-term care needs, and other financial challenges can affect the future you’ve worked hard to build.
In my book, Retirement By Design: How to Avoid Running Out of Money and Create the Income You Need, To Live the Way You Want!, I share strategies for identifying potential retirement risks, protecting your financial resources, and creating a retirement income plan around your goals.
Explore Retirement By Design and Get Your Copy →
Option 4: Medi-Cal and California Long-Term Care Benefits
For eligible California residents, Medi-Cal may help pay for certain long-term care services.
Medi-Cal is California’s Medicaid program, and it operates under different eligibility and coverage rules from Medicare.
Depending on eligibility and the program involved, Medi-Cal may help cover qualifying nursing facility care or certain home- and community-based services.
However, Medi-Cal is not automatically available to everyone who needs long-term care.
Understanding Medi-Cal Eligibility in 2026
California reinstated asset checks for certain Medi-Cal eligibility categories beginning January 1, 2026.
As of October 2026, the general asset limit for affected categories is $130,000 for one person, with additional allowances based on eligible household size.
Income, countable assets, medical needs, and program-specific requirements may all affect eligibility.
Certain assets may be excluded, and special protections may apply to married couples or registered domestic partners.
California has also announced further changes to asset limits beginning in July 2027, making it especially important to confirm the rules in effect when applying.
You can review current information through the California Department of Health Care Services.
Why Early Planning Matters
Medi-Cal eligibility can become complicated when retirement savings, property ownership, family finances, and long-term care needs overlap.
Families should not assume that transferring money or property to relatives will automatically help someone qualify.
Asset transfers, eligibility rules, estate recovery, and related issues deserve careful review with a qualified elder law attorney or benefits specialist.
A financial advisor can help evaluate how the possibility of needing long-term care fits into an overall retirement strategy, while legal and benefits professionals can address the applicable eligibility requirements.
Option 5: Veterans Benefits and Long-Term Care Assistance
Veterans and certain eligible family members may have access to additional resources.
Depending on eligibility, VA programs may provide or help cover services such as:
- Home health assistance
- Adult day healthcare
- Respite care
- Nursing home care
- Other qualifying long-term services and supports
Some veterans may also qualify for pension-related benefits, including Aid and Attendance, that can help with care-related expenses.
Eligibility may depend on service history, health needs, income, assets, service-connected disability status, and program availability.
Not all services or care facilities are fully funded by the VA. For example, VA generally does not pay assisted living room and board through its standard healthcare benefits.
Veterans and their families can explore available programs through the U.S. Department of Veterans Affairs.
This may be an important funding resource that some families overlook.
Option 6: Other Programs and Financial Resources
Long-term care planning is not always a choice between buying insurance and using savings.
Other resources may also play a role.
Social Security and Pension Income
Retirement income from Social Security or a pension may help cover a portion of ongoing care costs.
However, those payments may already be needed for housing, food, transportation, and other living expenses.
This is especially important for married couples when one spouse requires care and the other continues living independently.
Home Equity
For some homeowners, home equity may be a potential source of funds.
Options can include selling or downsizing a property or, in some circumstances, evaluating a home equity loan or reverse mortgage.
These decisions carry important financial and legal considerations, including borrowing costs, repayment obligations, potential effects on benefits, and what happens to a spouse who remains in the home.
Using home equity should never be treated as an automatic solution.
Programs of All-Inclusive Care for the Elderly (PACE)
PACE is another option some older adults may qualify for.
PACE programs coordinate certain healthcare and long-term services for eligible individuals, helping many participants continue living in their communities.
Generally, participants must be at least 55, live within a participating service area, require a nursing home level of care, and be able to live safely in the community with support.
Availability, eligibility, and out-of-pocket costs depend on the program and the individual’s circumstances.
Families can learn more through Medicare’s PACE information.
Does Medicare Pay for Long-Term Care?
This is one of the most important distinctions to understand.
Medicare generally does not pay for ongoing custodial long-term care.
That includes many services focused primarily on assistance with everyday activities, such as dressing, bathing, or personal supervision.
Medicare may cover certain skilled nursing facility services or home healthcare under specific conditions, but that coverage is different from paying for ongoing personal care over months or years.
Even someone with Medicare and supplemental insurance may face significant long-term care expenses.
I’ve covered this distinction in more detail in my article, Does Medicare Pay for Long-Term Care? What Retirees Need to Know.
Understanding what Medicare does and does not cover can help you avoid building a retirement plan around benefits that may not be available when you need them.
Comparing Long-Term Care Funding Options
Each funding method offers different benefits and limitations.
| Funding option | Potential advantage | Important consideration |
| Personal savings | Flexibility in how funds are used | May reduce retirement savings and income |
| Traditional LTC insurance | Dedicated benefits for qualifying care | Premiums, underwriting, and coverage limitations |
| Hybrid policies | Combines certain life insurance and care benefits | Costs, policy complexity, and reduced death benefits |
| Medi-Cal | May assist eligible individuals with qualifying care costs | Income, asset, medical, and program requirements |
| Veterans benefits | May provide qualifying services or financial assistance | Eligibility and service availability vary |
| Home equity | May provide access to additional financial resources | Borrowing costs, housing risks, and repayment obligations |
There is no single funding method that is best for everyone.
The objective is to understand which options are available, how they interact, and what each may mean for your retirement.
How Long-Term Care Planning Fits Into a Comprehensive Retirement Strategy
One of the biggest retirement planning mistakes I see is treating individual financial decisions as though they exist separately.
Investment accounts, Social Security, retirement income, insurance, taxes, healthcare, and estate planning are closely connected.
Long-term care is no exception.
For example, a decision about how much money to keep in savings could affect your portfolio strategy.
The purchase of an insurance policy could affect your retirement cash flow.
Large retirement account withdrawals could create additional tax considerations.
And decisions involving a home or other property could affect your spouse, your family, or your estate plan.
This is why I believe long-term care funding should be evaluated within a coordinated financial strategy.
Through my Retirement Planning Services in San Diego, I help individuals and families consider how retirement income, portfolio assets, financial risks, healthcare concerns, and long-term goals fit together.
Planning doesn’t eliminate uncertainty. It can help you make more informed decisions before the financial pressure of an unexpected care need arrives.
Five Questions to Ask Before Choosing How to Pay for Long-Term Care
Before making decisions about long-term care funding, I encourage you to consider these questions.
1. What Type of Care Would You Prefer?
Would you want to remain in your own home if possible? Would assisted living be an option? What if you eventually needed more specialized care?
Your preferences can affect the funding strategies you evaluate.
2. How Much Could You Afford Without Disrupting Retirement?
Consider what would happen if an additional care expense continued for one, two, or several years.
Would you need to sell portfolio assets? Reduce spending? Change your housing plans?
3. What Insurance Coverage Do You Already Have?
Some individuals have older long-term care insurance policies or employer-related benefits they haven’t reviewed recently.
Understanding existing coverage should come before purchasing anything new.
4. How Would Care Expenses Affect Your Spouse or Family?
A plan should consider more than the person receiving care.
Your spouse may still need financial resources for living expenses and their own future healthcare needs.
5. Who Should Be Involved in the Planning Conversation?
A coordinated approach may involve a financial advisor, insurance professional, CPA, estate planning attorney, elder law attorney, and family members.
Each can contribute expertise in a different area.
When Should You Start Planning for Long-Term Care?
Ideally, long-term care planning begins before a major health event creates an immediate need.
That gives you more time to understand your choices, evaluate potential insurance eligibility, and prepare your retirement finances.
Waiting until care becomes necessary can limit your options.
Insurance underwriting may become more difficult, and families may face urgent financial decisions under stressful circumstances.
For more on timing, read At What Age Should You Start Planning for Long-Term Care?.
You don’t need to predict exactly what your future healthcare needs will be. You simply need to recognize that preparing for different possibilities is an important part of retirement planning.
My Approach: Prepare for the Life You Want While Protecting Your Options
Throughout my career, I’ve believed that financial planning should help people create a life by design, not by default.
That philosophy applies to long-term care planning as well.
I don’t believe the goal should be to purchase every available financial product or prepare for every imaginable scenario.
Instead, the goal is to understand your financial circumstances and create a strategy around what matters most to you.
For some individuals, that may mean evaluating traditional long-term care insurance.
For others, it may involve comparing hybrid policies, setting aside portfolio assets, reviewing public benefits, or coordinating several funding sources.
What matters is that the decisions are intentional and fit into the larger picture of your retirement.
The question isn’t simply whether you can afford long-term care. It’s how you can prepare for potential care expenses while continuing to support the retirement lifestyle and financial goals that matter to you.
Let’s Talk About Your Retirement and Long-Term Care Planning
If you’re approaching retirement or concerned about how future healthcare and long-term care expenses could affect your savings, I invite you to start a conversation.
As a financial advisor in San Diego with more than 28 years of experience, I help individuals, families, and business owners develop personalized financial strategies designed around their goals.
Together, we can review how potential long-term care expenses may fit into your retirement income strategy, existing financial resources, and long-term plans.
Schedule Your Wealth Discovery Call
Call: (619) 640-2622
Serving: San Diego County, including La Jolla, Del Mar, Carlsbad, Encinitas, Rancho Santa Fe, Poway, Coronado, and surrounding communities.
Frequently Asked Questions About Paying for Long-Term Care
What is the best way to pay for long-term care?
The best approach depends on your financial resources, health, insurance eligibility, and retirement goals. Options include personal savings, traditional long-term care insurance, hybrid insurance policies, and qualifying public benefit programs. Some families use a combination of funding sources.
Can I pay for long-term care with my 401(k) or IRA?
Yes. You may be able to use withdrawals from your 401(k), IRA, or other retirement accounts to pay for care. However, distributions may have tax consequences and reduce the amount available for future retirement expenses. Reviewing the withdrawal strategy with qualified professionals is important.
Does Medicare cover assisted living or nursing home care?
Medicare generally does not cover ongoing custodial care, including most long-term stays primarily for assistance with daily activities. It may cover certain skilled nursing or rehabilitation services when eligibility requirements are met.
Is long-term care insurance worth buying in California?
Long-term care insurance may be valuable for some individuals, particularly those who want to evaluate coverage for qualifying care expenses rather than rely entirely on savings. Whether it makes sense depends on premiums, available benefits, health, financial circumstances, and policy provisions.
Can Medi-Cal help pay for nursing home care in San Diego?
Medi-Cal may help eligible California residents pay for qualifying nursing facility care. Eligibility depends on factors including income, assets, medical needs, and applicable program requirements. Because eligibility rules can change, verify current requirements with the California Department of Health Care Services.
What happens if I cannot afford long-term care?
Depending on your financial and medical circumstances, you may qualify for assistance through Medi-Cal or other programs. Veterans may have additional benefits available. A benefits specialist, qualified elder law attorney, or local aging-services organization can help you understand applicable options.
Should I use savings or purchase long-term care insurance?
That decision depends on how much financial risk you can comfortably retain, the type of insurance available, the cost of coverage, and your other retirement obligations. Comparing projected expenses with available resources can help clarify which approach may be appropriate.